1
Apply Your Land Equity
The documented value of land you own free and clear may be credited toward the applicable down-payment requirement.
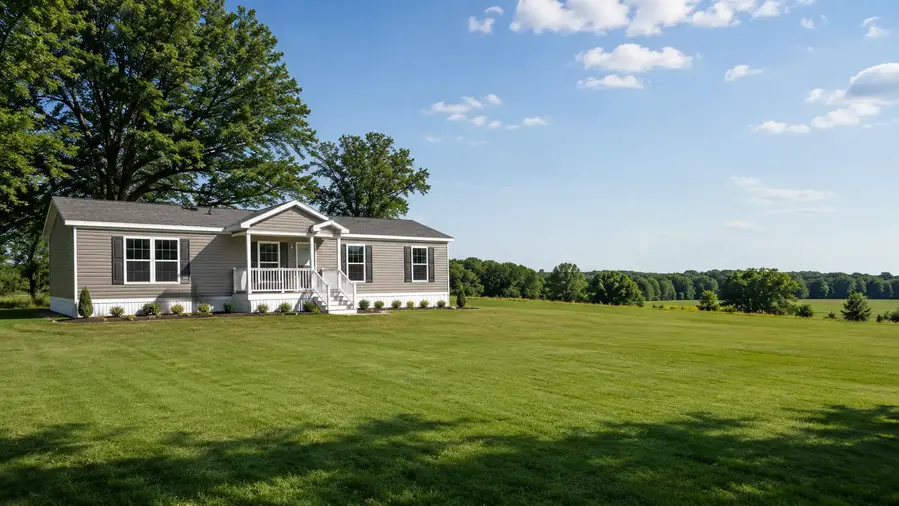
Have you found the perfect manufactured or mobile home on MHVillage.com, or do you already have a floor plan picked out with a retailer? If you own eligible land, its equity may satisfy the down-payment requirement—so you may not need to bring a cash down payment.
Complete this quick form and Bobby will review your scenario directly.
Your Land-In-Lieu inquiry was sent directly to Bobby.
For a faster response, text 904-789-0012.
Eligible land equity can replace some or all of the down payment on a manufactured or mobile home loan.
The documented value of land you own free and clear may be credited toward the applicable down-payment requirement.
When land equity covers the full required down payment, you may be able to preserve cash for moving expenses or other needs.
Through the Land-In-Lieu program, eligible equity in your land may be applied toward the required down payment. The loan has a fixed interest rate, and the monthly payment includes principal and interest. There is no prepayment penalty, so you may pay off the loan early without an additional charge.
Land-in-Lieu financing is designed for buyers who own eligible land free and clear, plan to place a manufactured or mobile home on that property, and want to apply a portion of the documented land value toward the home’s required down payment.
Florida, Texas, Michigan, Oregon, Idaho, or Washington.
Loan amounts: $35,000–$450,000.
600 or higher: 5% minimum down payment, and the land must provide at least 5% equity.
550–599: 15% minimum down payment. At least 5% must come from land equity. The remaining 10% can come from cash, check, land equity, or a combination.
The customer must currently own a primary home. A 15% minimum down payment is required, with at least 10% from land equity. The remaining 5% can come from cash, check, land equity, or a combination.
There is no minimum distance requirement. A home placed on the same land or at the same address as the primary residence is a Buy-For and is not eligible.
If the customer or co-applicant owns another home and will retain it, underwriting will require a 15% down payment—even when the new home will be the customer’s primary residence if the existing home is not sold before closing. At least 10% would come from land equity, and the remaining 5% can come from cash, check, land equity, or a combination.
No mortgages, loans, or other liens are permitted.
Enter the amount of cash you plan to contribute. Enter 0 if you plan to use land equity only.
Not sure what rate to use? Rates vary based on your credit score and loan details. Text Bobby for a current estimated rate.
Text Bobby to Get Your RateThis estimate uses the lender’s combined-value calculation and your entered cash down payment.
Estimate only. The land must be owned free and clear, and its value must be supported by acceptable documentation. The monthly payment uses the estimated loan amount after applying any entered cash contribution above the calculated minimum, and includes principal and interest only. It does not include insurance, property taxes, utilities, appraisal costs, or other charges that may apply. Actual loan amount, interest rate, term, payment, eligibility, and final requirements are subject to lender guidelines, underwriting, property eligibility, and approval.
Land-in-Lieu financing involves both the manufactured or mobile home and the customer-owned land. Bobby coordinates each stage—from pre-approval through funding—so you always know what is required and what comes next.
Select “See If I Qualify” to submit your initial request, or contact Bobby directly by text or phone. Bobby will personally follow up to learn about the home you want to purchase, your estimated land value, intended occupancy, and credit profile before explaining your available options and next steps.
See If I QualifyBobby reviews your loan application and submits it to the underwriter for initial loan approval. Your land must be owned free and clear, with no mortgages, loans, liens, or land-contract balances.
Once you select your manufactured or mobile home, Bobby communicates directly with the factory or retailer to confirm that eligible transportation and setup costs are included in the sales price and reflected in the purchase agreement.
Bobby also coordinates ordering of the home appraisal, title search or abstract, and any remaining lender or underwriting requirements.
Bobby balances the final figures, prepares the closing package, and coordinates with the lender, factory or retailer, appraiser, and other parties. After closing, the factory or retailer transports and sets the home on your land.
Once setup is complete, the appraiser returns to update the appraisal report. Bobby then submits the funding request, and after funding, the seller’s proceeds are wired or mailed directly to the factory or retailer.

I’m Bobby Jay, a mortgage professional with more than 20 years of experience. I specialize in land-in-lieu financing for buyers who own their land free and clear and want to purchase a manufactured or mobile home from a factory or retailer, then have it transported to and set up on their property.
I work directly with you, the lender, factory or retailer, and appraiser to keep every stage organized—from pre-approval through closing, home setup, and final funding.
You get one dedicated point of contact from pre-approval through final funding. Land-in-lieu financing involves more than approving the home—it requires verifying the land, reviewing the factory or retailer’s purchase agreement, accounting for transportation and setup costs, and completing the post-setup appraisal before the loan can be funded. Bobby manages these details so the transaction continues moving forward.
Get specialized experience with financing manufactured and mobile homes for buyers who own their land free and clear. Bobby understands how the land value, home sales price, transportation and setup costs, property documentation, and lender requirements work together within a land-in-lieu transaction.
Bobby personally reviews your loan application, discusses your goals, and identifies the documentation needed for the lender. He works quickly to submit a complete file for an initial underwriting decision and a same-day response whenever possible.
Bobby communicates directly with the factory or retailer to confirm that eligible transportation and setup costs are included in the sales price and properly reflected in the purchase agreement. He also coordinates the appraisal, title search or abstract, and any remaining lender or underwriting requirements.
Bobby remains hands-on through the finish line—balancing the final figures, preparing the closing package, and coordinating with the lender, factory or retailer, and appraiser. After closing and home setup, Bobby obtains the updated appraisal report, submits the final funding request, and ensures the seller’s proceeds are sent directly to the factory or retailer.
Provide the current or prior-year tax assessment in the customer’s name. If you do not have the assessment or believe the land is worth more, Bobby can order an independent land appraisal, paid out of pocket by the customer.
Lenders use a specialized plans-and-specs appraisal through DATA COMP to verify the market value of the manufactured home independently of the land asset. Bobby will order the appraisal, which must be paid out of pocket by the customer. The appraiser will inspect the home on the lot, and the appraisal will be completed subject to delivery and set.
The home must appraise at or above the final sales price. The appraisal is for the home only and will not take current or future land improvements into account.
A title search or abstract is required to confirm ownership and verify that the land is free and clear of active mortgages, tax liens, judgments, or other liens. No title insurance policy is required. Bobby will order the title search or abstract.
Up to $25,000 in eligible land improvements may be added to the sales price or financed directly into the loan amount. Examples may include permits, utility hookups, electrical service or a light pole, well installation, septic systems, and other eligible improvements. If the customer wants to finance the improvements into the loan amount, an estimate from the local company that will complete the work is required.
For eligible transactions, a seller-paid credit equal to 4% of the customer’s loan amount may lower the customer’s interest rate by 1%. The amount may be added to the sales price, subject to appraisal, program, and lender limits. Bobby can provide the appropriate purchase-agreement wording for the transaction.
Yes. Eligible equity in land you own free and clear may be applied toward the required down payment. If the eligible land equity covers the full down-payment requirement, the transaction may require $0 cash down from the customer.
Yes. Specialized manufactured home lenders offer these programs. At themobilehomeloanguy.com, Bobby Jay works directly with niche lenders that accept eligible land equity toward the required down payment, subject to lender guidelines and approval.
No. The land-in-lieu program is a specialized chattel, home-only program that uses eligible customer-owned land as additional collateral.
Gifted or inherited land may be eligible once the deed has been legally transferred into the customer’s name and the land is owned free and clear, subject to documentation, underwriting, and lender approval.
Yes. Under current Land-In-Lieu guidelines, the land must be owned free and clear. There can be no active mortgages, liens, or land-contract balances remaining on the property.
Value is established using a current or prior-year local tax assessment in the customer’s name. If a higher valuation is needed to cover the down payment, Bobby can order an independent land appraisal paid out of pocket by the customer.
Yes. The Land-In-Lieu program may allow eligible pre-owned manufactured homes built in 1977 or newer that have been moved more than once, subject to the home, title, condition, appraisal, documentation, lender requirements, and final approval.
Yes. Qualifying second homes require a minimum 625 credit score and 15% down, with at least 10% from eligible land equity. The customer must own a primary residence, and the new home must be placed at a different address on separate land. A home placed on the same land or at the same address as the primary residence is classified as a Buy-For transaction and is not eligible.
Yes. Eligible closing costs may be financed directly into the loan package, minimizing the cash needed at closing, subject to current program requirements and final approval.
No. One of the primary benefits of the Land-In-Lieu structure is that it does not require PMI, which avoids adding a monthly private mortgage insurance charge to the customer’s payment.
Send Bobby your information and find out whether Land-In-Lieu may fit your purchase.